

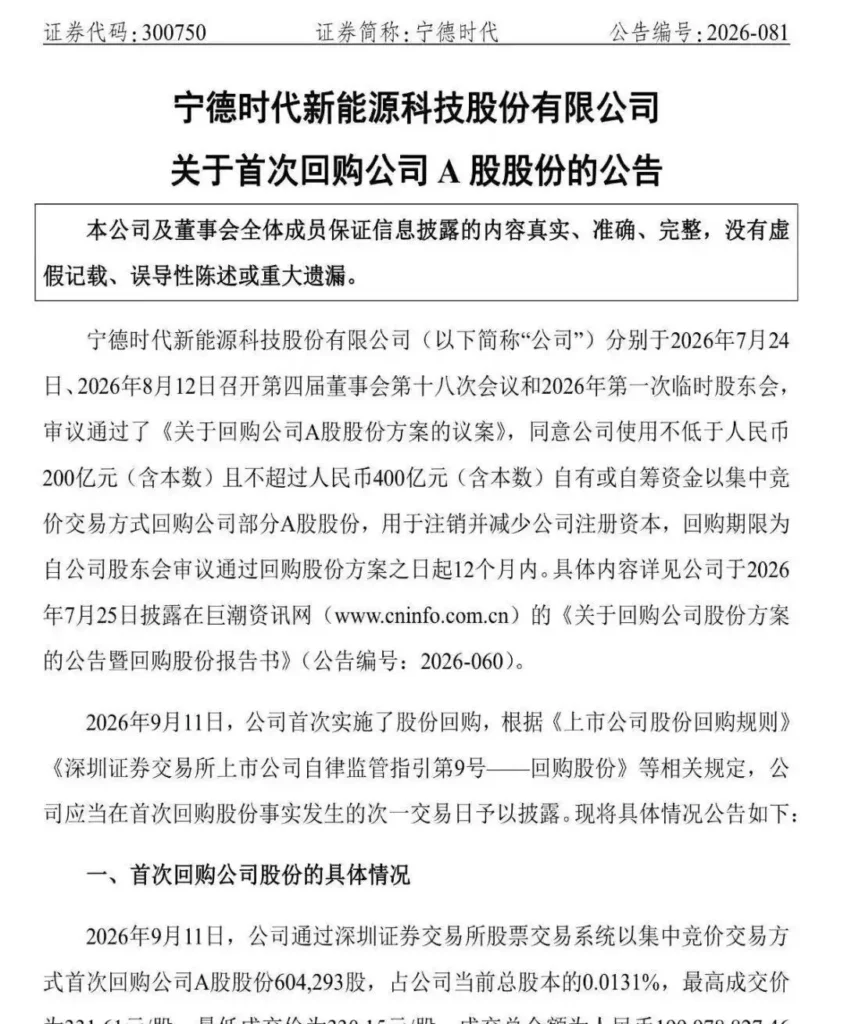
A roughly 1.1 billion yuan CATL share buyback was disclosed late on Sept. 21, with the battery maker saying it had repurchased 3.6875 million A-shares via the Shenzhen Stock Exchange at prices between 296.26 and 301 yuan per share.
CATL Share Buyback: How the Deal Was Structured
The repurchased shares are intended for cancellation rather than resale, which would reduce CATL’s outstanding float once the cancellation is completed. CATL shares rose 3.21% the next day, Sept. 22, to close at 306.64 yuan.
State Media Rejects ‘De-CATL’ Narrative
An outlet affiliated with China’s Ministry of Industry and Information Technology (MIIT) published an article dismissing the recently recurring “de-CATL-ization” narrative as a public-opinion farce.
The outlet argued that automakers adding second suppliers, developing in-house battery technology or adjusting procurement ratios are routine business decisions, not evidence of a battle to replace the leading battery maker. It said the real risk is not whether automakers have a second supplier, but attempts to frame ordinary supply-chain diversification as a camp war over market dominance.
Energy Storage Sector Faces Scrutiny
Since June, shares of energy-storage supply chain companies — including CATL, Hithium, Deye and Sungrow — have underperformed the broader market. Investors have cited concerns over whether China’s energy-storage demand will cool next year, whether geopolitical tensions could restrict overseas markets, and whether further declines in battery prices would erode profitability.
JPMorgan Sees Overreaction, Keeps Bullish Call
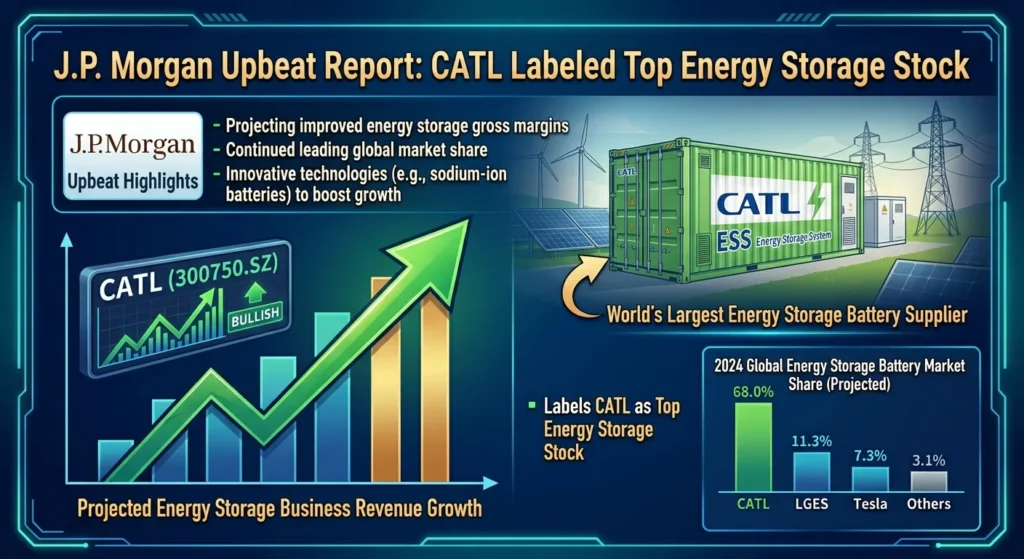
JPMorgan said the recent sell-off in the energy-storage sector is an overreaction and maintained a positive view on storage demand through 2030. The bank forecasts China’s energy-storage installed capacity will grow at a compound annual rate of about 22% through 2030, with battery shipments rising by roughly 20% year-on-year in 2027, compared with market expectations of near-zero growth.
JPMorgan named CATL, Sungrow and Deye as its top picks in the sector and identified CATL as better positioned to participate in global energy-storage growth, citing its leading market share, strong overseas exposure and a more attractive valuation after the pullback. The bank set a price target of HK$725 for CATL’s Hong Kong-listed shares.